

How to Make an App Like M1 Finance
How to Make an App Like M1 Finance
M1 Finance changed the way everyday investors think about building wealth. By blending automated investing, fractional shares, borrowing, and banking into a single "Finance Super App," M1 proved there's enormous appetite for platforms that make sophisticated money management feel effortless.
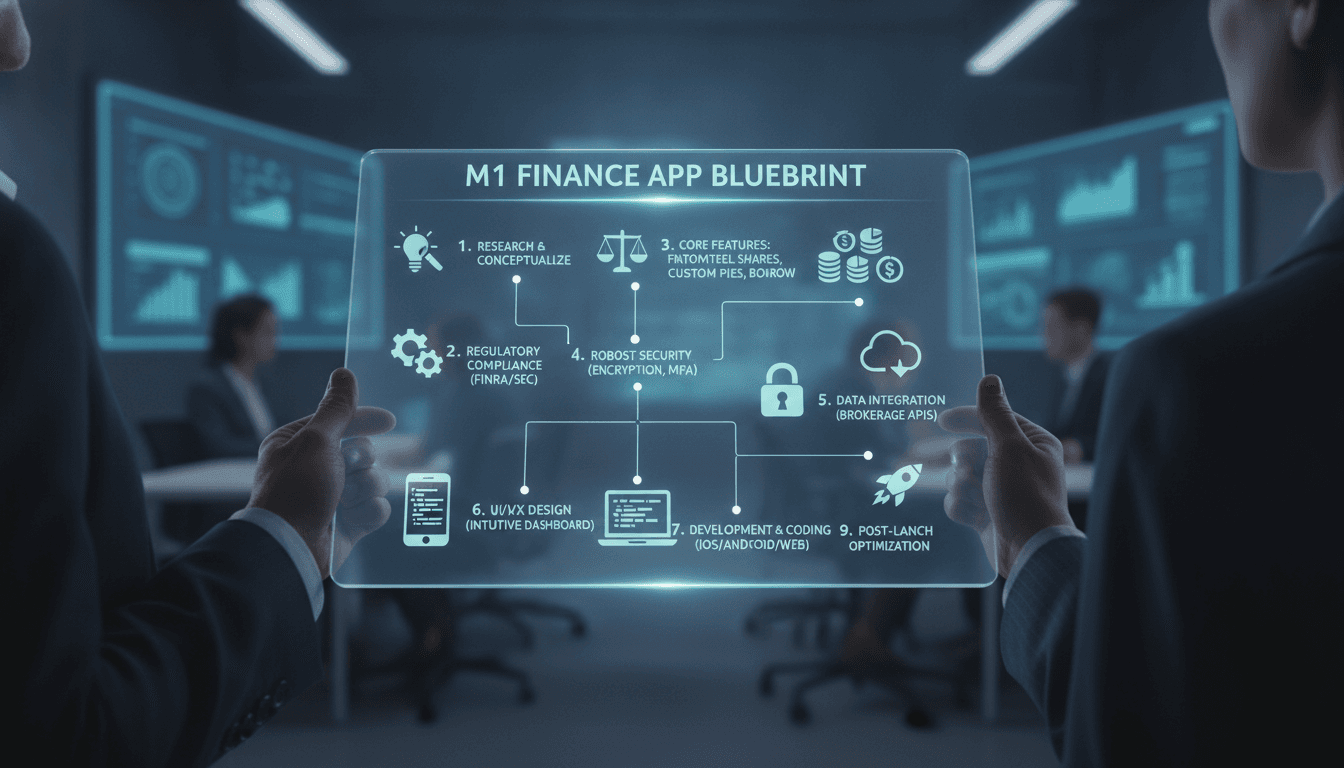
If you're planning to build something similar, this guide walks you through the features, architecture, compliance requirements, tech stack, timeline, and costs involved in creating a robo-advisory investment app.
What Exactly Is M1 Finance?
M1 Finance is a hybrid investing platform that sits somewhere between a traditional brokerage and a robo-advisor. Users create a "Pie" — a visual portfolio made up of slices, where each slice represents a stock, ETF, or another Pie with a target allocation percentage.
When money is deposited, M1 automatically buys fractional shares to keep the portfolio aligned with those targets. There's no manual trade-by-trade decision-making required, but users retain full control over what goes into their portfolio — something pure robo-advisors don't offer.
Around that core, M1 layers additional revenue-generating products:
- M1 Invest — taxable brokerage accounts, IRAs, trusts, and custodial accounts
- M1 Borrow — a portfolio line of credit against margin-eligible holdings
- M1 Spend — a checking account and debit card with cash-back rewards
- M1 Plus — a paid subscription tier unlocking lower borrow rates, higher rewards, and extra trade windows
Understanding this ecosystem matters because the app's stickiness comes from the interconnection of these products, not from any single feature.
Why Build a Fintech Investment App Now?
The market conditions remain favorable for new entrants, especially those targeting underserved niches:
- Retail investing is now mainstream. Commission-free trading permanently lowered the barrier to entry, and a generation of investors expects a mobile-first experience.
- Fractional shares democratized access. Users can build diversified portfolios with $10 instead of $10,000.
- Robo-advisory assets keep climbing. Automated investment platforms manage trillions globally and continue to grow at double-digit rates.
- Embedded finance infrastructure matured. APIs from clearing firms, custodians, and KYC providers mean you no longer need to build a brokerage from scratch.
- Niche positioning wins. Platforms focused on specific communities — faith-based investing, ESG portfolios, expat investors, teen accounts, or particular professions — can capture loyal audiences that broad players ignore.
Core Features Your App Needs
1. Onboarding, KYC, and Account Opening
This is where most fintech apps lose users. Every abandoned step costs you a customer.
- Email/phone signup with biometric and 2FA login
- Identity verification (government ID scan, selfie liveness check, SSN or national ID)
- KYC/AML screening against sanctions and PEP watchlists
- Risk tolerance and investment objective questionnaire
- Account type selection (individual, joint, retirement, custodial)
- Digital signing of customer agreements
Target a sub-five-minute onboarding flow. Use progressive disclosure — ask only what's legally required up front, and collect the rest later.
2. Portfolio Builder ("Pies" Equivalent)
The signature feature. Users should be able to:
- Create custom portfolios with percentage-based allocations
- Nest portfolios inside other portfolios
- Choose from expert-curated model portfolios
- Visualize allocations with interactive charts
- Edit targets and see projected rebalancing impact before confirming
The drag-and-adjust allocation interface is your product's personality. Invest heavily in making it feel tactile and instantly responsive.
3. Fractional Share Trading
Fractional investing requires an order management system that can:
- Aggregate user orders into whole-share block trades
- Allocate fractional positions internally across accounts
- Handle trade windows (batch execution at set times rather than continuous trading)
- Manage cash sweeps and residual balances
- Reconcile positions daily with your clearing partner
This is one of the hardest parts to build correctly. Precision matters — accounting errors at the fractional level compound fast.
4. Automated Rebalancing and Dynamic Deposits
When a user deposits funds, the system should calculate which slices are furthest below target and direct new money there first. Features to include:
- Deposit-driven rebalancing
- Full portfolio rebalancing on demand
- Automatic dividend reinvestment
- Scheduled recurring transfers (daily, weekly, biweekly, monthly)
- Tax-efficient sell ordering for withdrawals
5. Funding and Banking Connections
- ACH bank linking via aggregators (Plaid, MX, Yodlee)
- Wire transfers and check deposits
- ACATS transfers to bring in accounts from other brokerages
- Instant deposit availability up to a threshold
- Withdrawal scheduling and limits
6. Portfolio Dashboard and Analytics
- Real-time and end-of-day portfolio value
- Performance charts across multiple time horizons
- Money-weighted vs. time-weighted returns
- Gain/loss breakdown by position (realized and unrealized)
- Dividend income tracking
- Allocation drift indicators
7. Margin Lending
If you replicate M1 Borrow, you'll need:
- Real-time margin eligibility and borrowing capacity calculation
- Loan-to-value monitoring and maintenance requirements
- Automated margin call notifications and liquidation logic
- Interest accrual and statement generation
Margin lending significantly increases your regulatory and risk-management burden. Many teams launch without it and add it in year two.
8. Cash Management and Debit Card
Delivered through a sponsor bank via Banking-as-a-Service providers:
- FDIC-insured checking or sweep accounts
- Physical and virtual debit cards
- Card controls (freeze, spending limits, PIN reset)
- Cash-back or rewards engine
- Bill pay and peer transfers
9. Tax Documents and Reporting
- Automated 1099-B, 1099-DIV, 1099-INT generation (or local equivalents)
- Cost basis tracking with configurable lot selection methods
- Wash sale detection
- Downloadable statements and trade confirmations
- Export to tax software
10. Education and Engagement
- In-app explainers for investing concepts
- Goal-setting and progress tracking
- Push notifications for deposits, dividends, and drift alerts
- Referral program with incentives
Regulatory and Compliance Foundations
This is the part that separates fintech from ordinary app development. You cannot ship first and figure out compliance later.
Licensing Paths
Option A: Become a registered broker-dealer. You'll need FINRA membership, SEC registration, a Series 24 principal, net capital requirements, and a compliance program. Expect 9–18 months and substantial legal costs — but you own the economics and the user relationship end to end.
Option B: Register as an RIA and partner with a custodian. Register as an investment adviser with the SEC or your state, then use a third-party custodian and clearing firm for execution. Far faster to market and dramatically cheaper.
Option C: Broker-dealer as a service. Providers like Apex Clearing, DriveWealth, Alpaca, or Atomic offer APIs that handle account opening, custody, execution, and regulatory reporting. You build the experience; they carry much of the regulatory weight. This is how most modern investing apps launch.
For non-US markets, the equivalents matter just as much — FCA authorization in the UK, SEBI registration in India, ASIC in Australia, and so on.
Ongoing Obligations
- KYC/AML program with a designated compliance officer
- Suspicious activity monitoring and reporting
- Books and records retention
- Marketing and advertising review (performance claims are heavily restricted)
- Data privacy compliance (GDPR, CCPA, GLBA)
- Regular audits and regulatory examinations
Budget for a dedicated compliance hire or a fractional compliance consultant from day one.
Technical Architecture
Recommended Stack
Mobile front end
- React Native or Flutter for cross-platform efficiency
- Native Swift/Kotlin if you need maximum performance for real-time charting
- Victory Native, Recharts, or D3 for data visualization
Backend
- Node.js (NestJS), Python (FastAPI/Django), Go, or Java Spring Boot
- Microservices for account management, portfolio engine, order management, ledger, notifications, and reporting
- Event-driven communication via Kafka or RabbitMQ
Data layer
- PostgreSQL for transactional and ledger data (ACID guarantees are non-negotiable)
- Redis for caching quotes and session data
- TimescaleDB or ClickHouse for time-series market and performance data
- S3-compatible object storage for documents and statements
Infrastructure
- AWS, GCP, or Azure with multi-AZ redundancy
- Kubernetes for orchestration
- Infrastructure-as-code via Terraform
- Comprehensive observability (Datadog, Grafana, Sentry)
Third-Party Integrations You'll Rely On
| Function | Example Providers |
|---|---|
| Clearing & custody | Apex Clearing, DriveWealth, Alpaca, Pershing |
| Market data | Polygon.io, IEX Cloud, Refinitiv, Nasdaq |
| Bank linking | Plaid, MX, Yodlee, Finicity |
| Identity & KYC | Persona, Alloy, Onfido, Jumio |
| Banking & cards | Unit, Synapse, Treasury Prime, Marqeta |
| Payments/ACH | Dwolla, Modern Treasury, Stripe |
| Tax reporting | Handled by clearing partner or specialized vendors |
The Ledger Is Your Backbone
Build a double-entry ledger from the beginning. Every deposit, trade, dividend, fee, and withdrawal must be recorded as balanced journal entries. Retrofitting a proper ledger after launch is one of the most painful migrations a fintech team can face — and reconciliation breaks will destroy user trust faster than any bug.
Security Requirements
- Encryption at rest (AES-256) and in transit (TLS 1.3)
- Secrets management via HashiCorp Vault or cloud KMS
- Biometric authentication and mandatory MFA
- Device fingerprinting and anomaly detection
- Role-based access control with least-privilege internal permissions
- SOC 2 Type II certification
- Penetration testing before launch and annually thereafter
- Immutable audit logs for every account-affecting action
Development Roadmap
Phase 1 — Discovery and Compliance (6–10 weeks) Market research, regulatory strategy, partner selection, product requirements, and technical architecture.
Phase 2 — Design (6–8 weeks) Wireframes, user flows, design system, high-fidelity screens, and clickable prototypes. Usability-test the portfolio builder aggressively.
Phase 3 — Core Build (16–24 weeks) Onboarding and KYC, account funding, portfolio engine, order management, ledger, and dashboard.
Phase 4 — Integrations and Extended Features (8–12 weeks) Recurring investing, dividend reinvestment, tax documents, notifications, and optional borrow/spend modules.
Phase 5 — Testing and Certification (6–10 weeks) QA, security audits, clearing firm certification, compliance review, and regulatory sign-off.
Phase 6 — Launch and Iteration (ongoing) Beta with a limited cohort, monitored rollout, then continuous improvement.
Realistic total for an MVP: 9 to 14 months.
Cost Breakdown
Costs vary widely by region and scope, but here's a working framework:
MVP (core investing, custodian-partnered): $150,000 – $300,000 Full-featured platform (invest + borrow + spend): $350,000 – $750,000+
Additional line items often underestimated:
- Legal and regulatory setup: $50,000 – $200,000
- Compliance staffing: $80,000 – $150,000 annually
- Market data licensing: $2,000 – $20,000+ monthly depending on redistribution rights
- Clearing firm minimums and per-account fees
- Security audits and SOC 2: $30,000 – $80,000
- Cloud infrastructure: $3,000 – $15,000 monthly at moderate scale
Offshore and nearshore development partners can reduce build costs by 40–60% without sacrificing quality — provided they have genuine fintech experience and understand regulated environments.
Monetization Models
- Premium subscription — M1's approach; a flat monthly or annual fee for enhanced features
- Net interest margin — earnings on uninvested cash balances
- Margin lending interest — typically the highest-margin product
- Payment for order flow — legal in some jurisdictions, controversial and increasingly scrutinized
- AUM fees — a percentage of assets under management, standard for advisory models
- Interchange revenue — from debit card transactions
- Securities lending — revenue from lending out customer shares
- White-label licensing — offering your platform to banks, credit unions, or advisors
Most successful platforms blend three or four of these rather than relying on one.
Common Pitfalls to Avoid
Underestimating reconciliation. Daily position and cash reconciliation with your clearing partner is operationally demanding. Build tooling for it early.
Treating compliance as a checkbox. Marketing copy, push notification wording, and even chart defaults can trigger regulatory issues. Get compliance involved in product design, not just at the end.
Over-engineering the MVP. Launch with one account type and a handful of well-tested features rather than a half-working version of everything.
Ignoring customer support infrastructure. Money apps generate high-stakes support tickets. A missing deposit is an emergency to your user. Staff and tool accordingly.
Skipping the education layer. Users who don't understand what they own churn quickly and make emotional decisions during volatility.
Neglecting performance during market stress. Your traffic will spike exactly when markets crash. Load-test for 10x normal volume.
How to Differentiate
Cloning M1 feature-for-feature isn't a strategy. Consider:
- Niche audiences — physicians, military families, freelancers, immigrants sending money home
- Thematic portfolios — climate, faith-aligned, local-economy, or sector-specific model portfolios
- AI-driven guidance — personalized rebalancing suggestions, spending insights, and natural-language portfolio Q&A
- Social investing — follow and copy vetted portfolios from trusted creators
- Geographic expansion — many markets still lack a credible fractional-investing platform
- Employer integration — payroll-linked automatic investing
Final Thoughts
Building an app like M1 Finance is genuinely difficult — but it's more achievable today than at any point in history. The infrastructure layer has matured to the point where a well-funded team with the right partners can launch a credible investing platform in about a year.
The differentiators aren't technical anymore. They're product judgment, regulatory diligence, operational rigor, and a clear point of view about who you're serving and why. Get those right, and the technology becomes a solvable problem.
If you're planning a fintech product and need a team that understands both the engineering and the regulatory terrain, the right development partner will save you far more than they cost — mostly by helping you avoid the mistakes that sink first-time fintech builders.
Have a project in mind? Contact Sodio Technologies to discuss your requirements and explore the right technology solution for your business.
/// Work with us
Talk to the engineers who'd build it
You'll get a technical scope, timeline and cost estimate from the people doing the work, not an account manager. In-house team, no subcontracting, since 2016.